
Author: Julie
October / November 2026 Housing Update
November 10, 2026The biggest story for October and November is higher interest rates. Rates eased a little in late October, but they’re still above 7% and more than a full point higher than a year ago. Buyers have felt it.
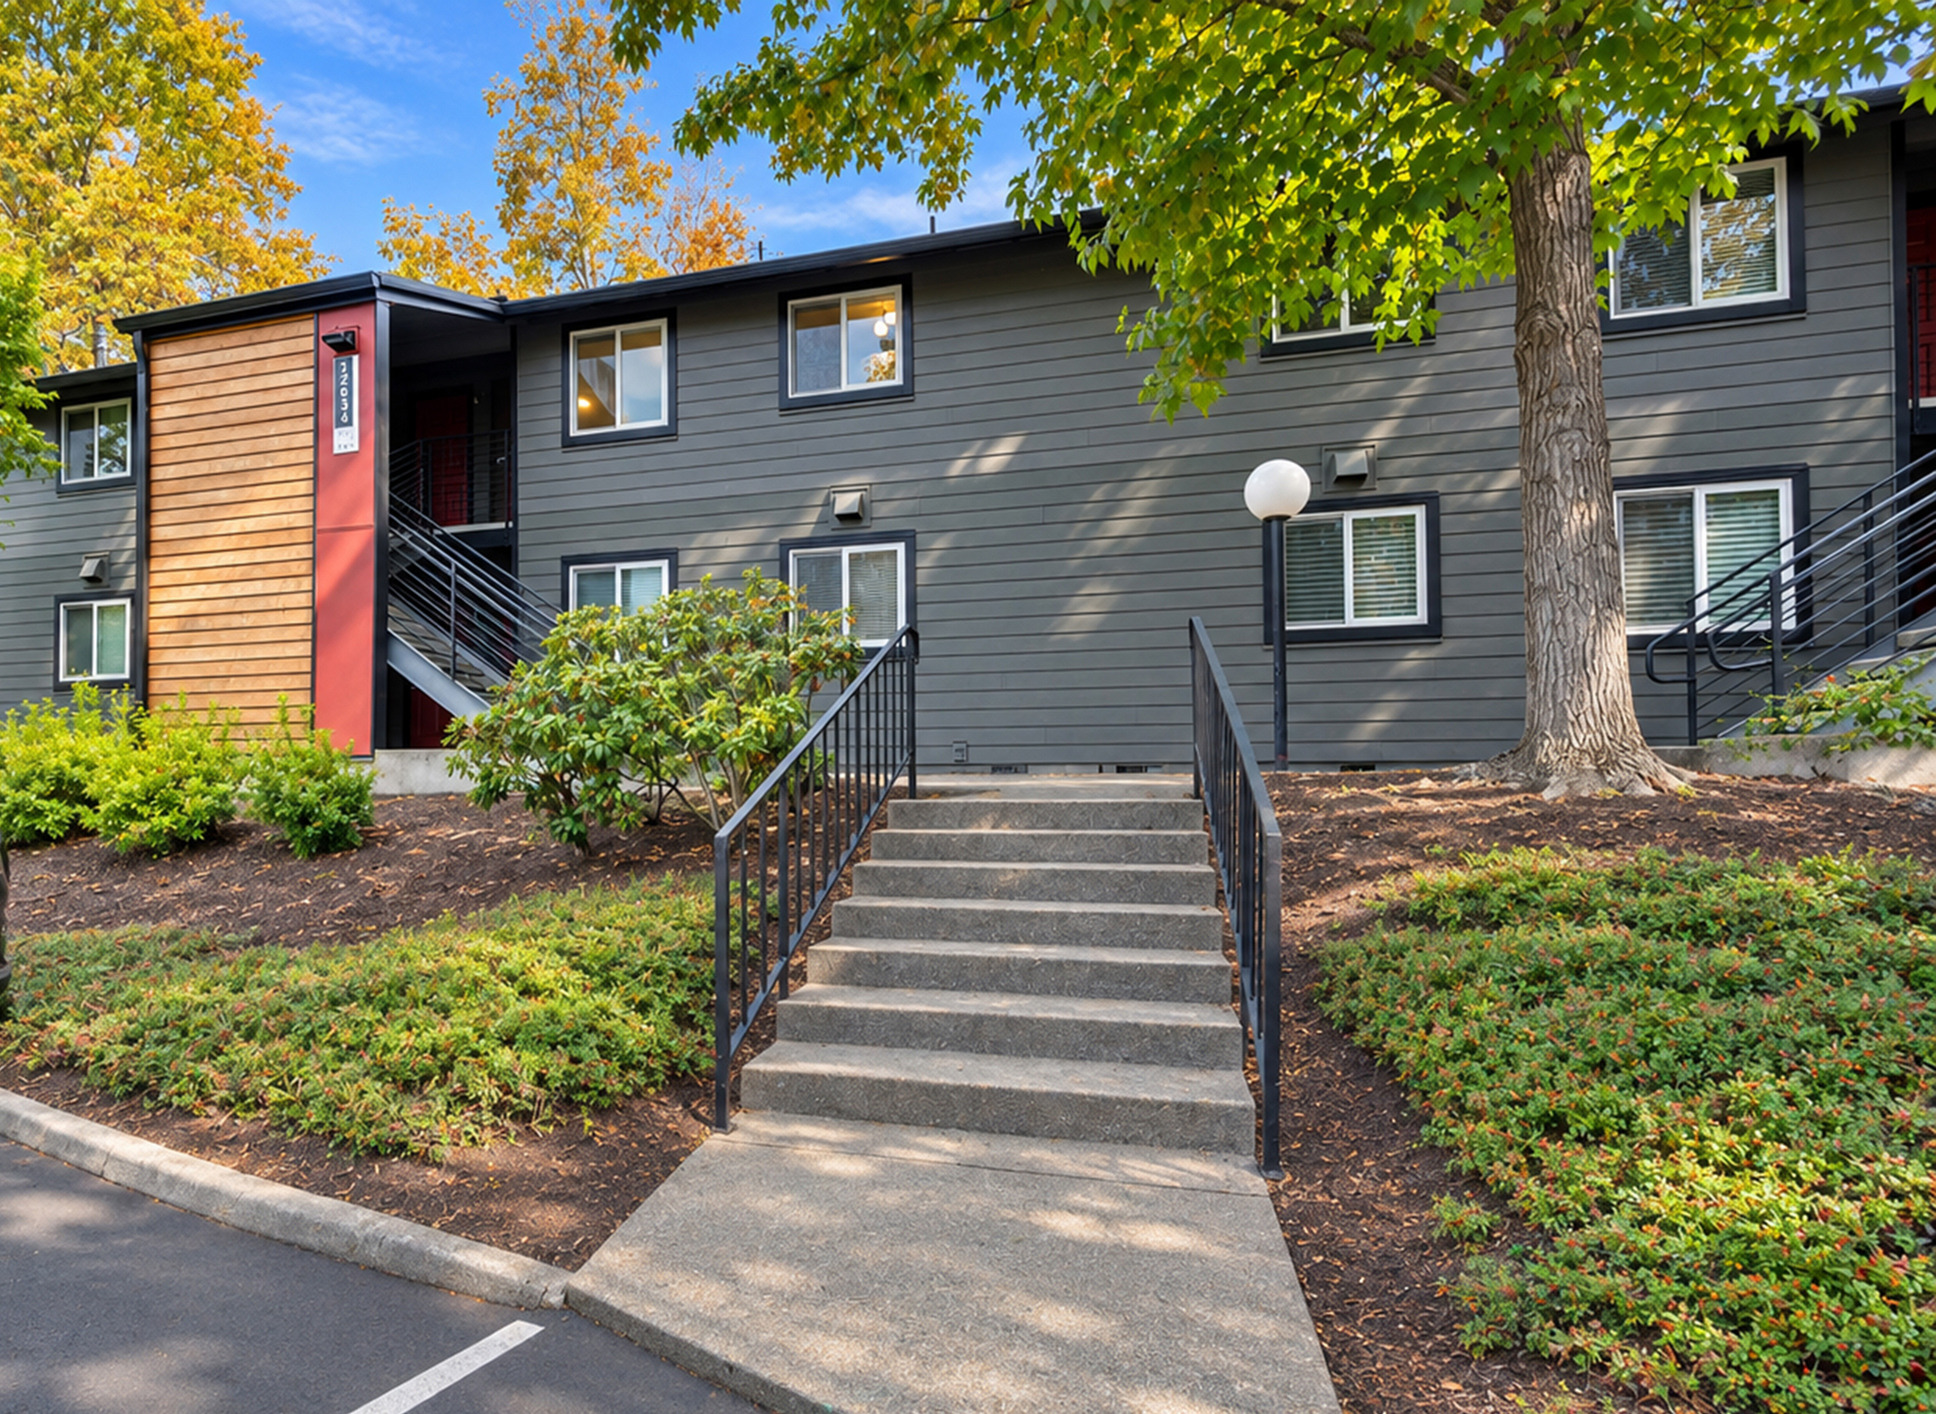
One-Bedroom Cedar Mill Condo with a Garage at Westlake Village
November 9, 2026One-Bedroom Cedar Mill Condo with a Garage at Westlake Village
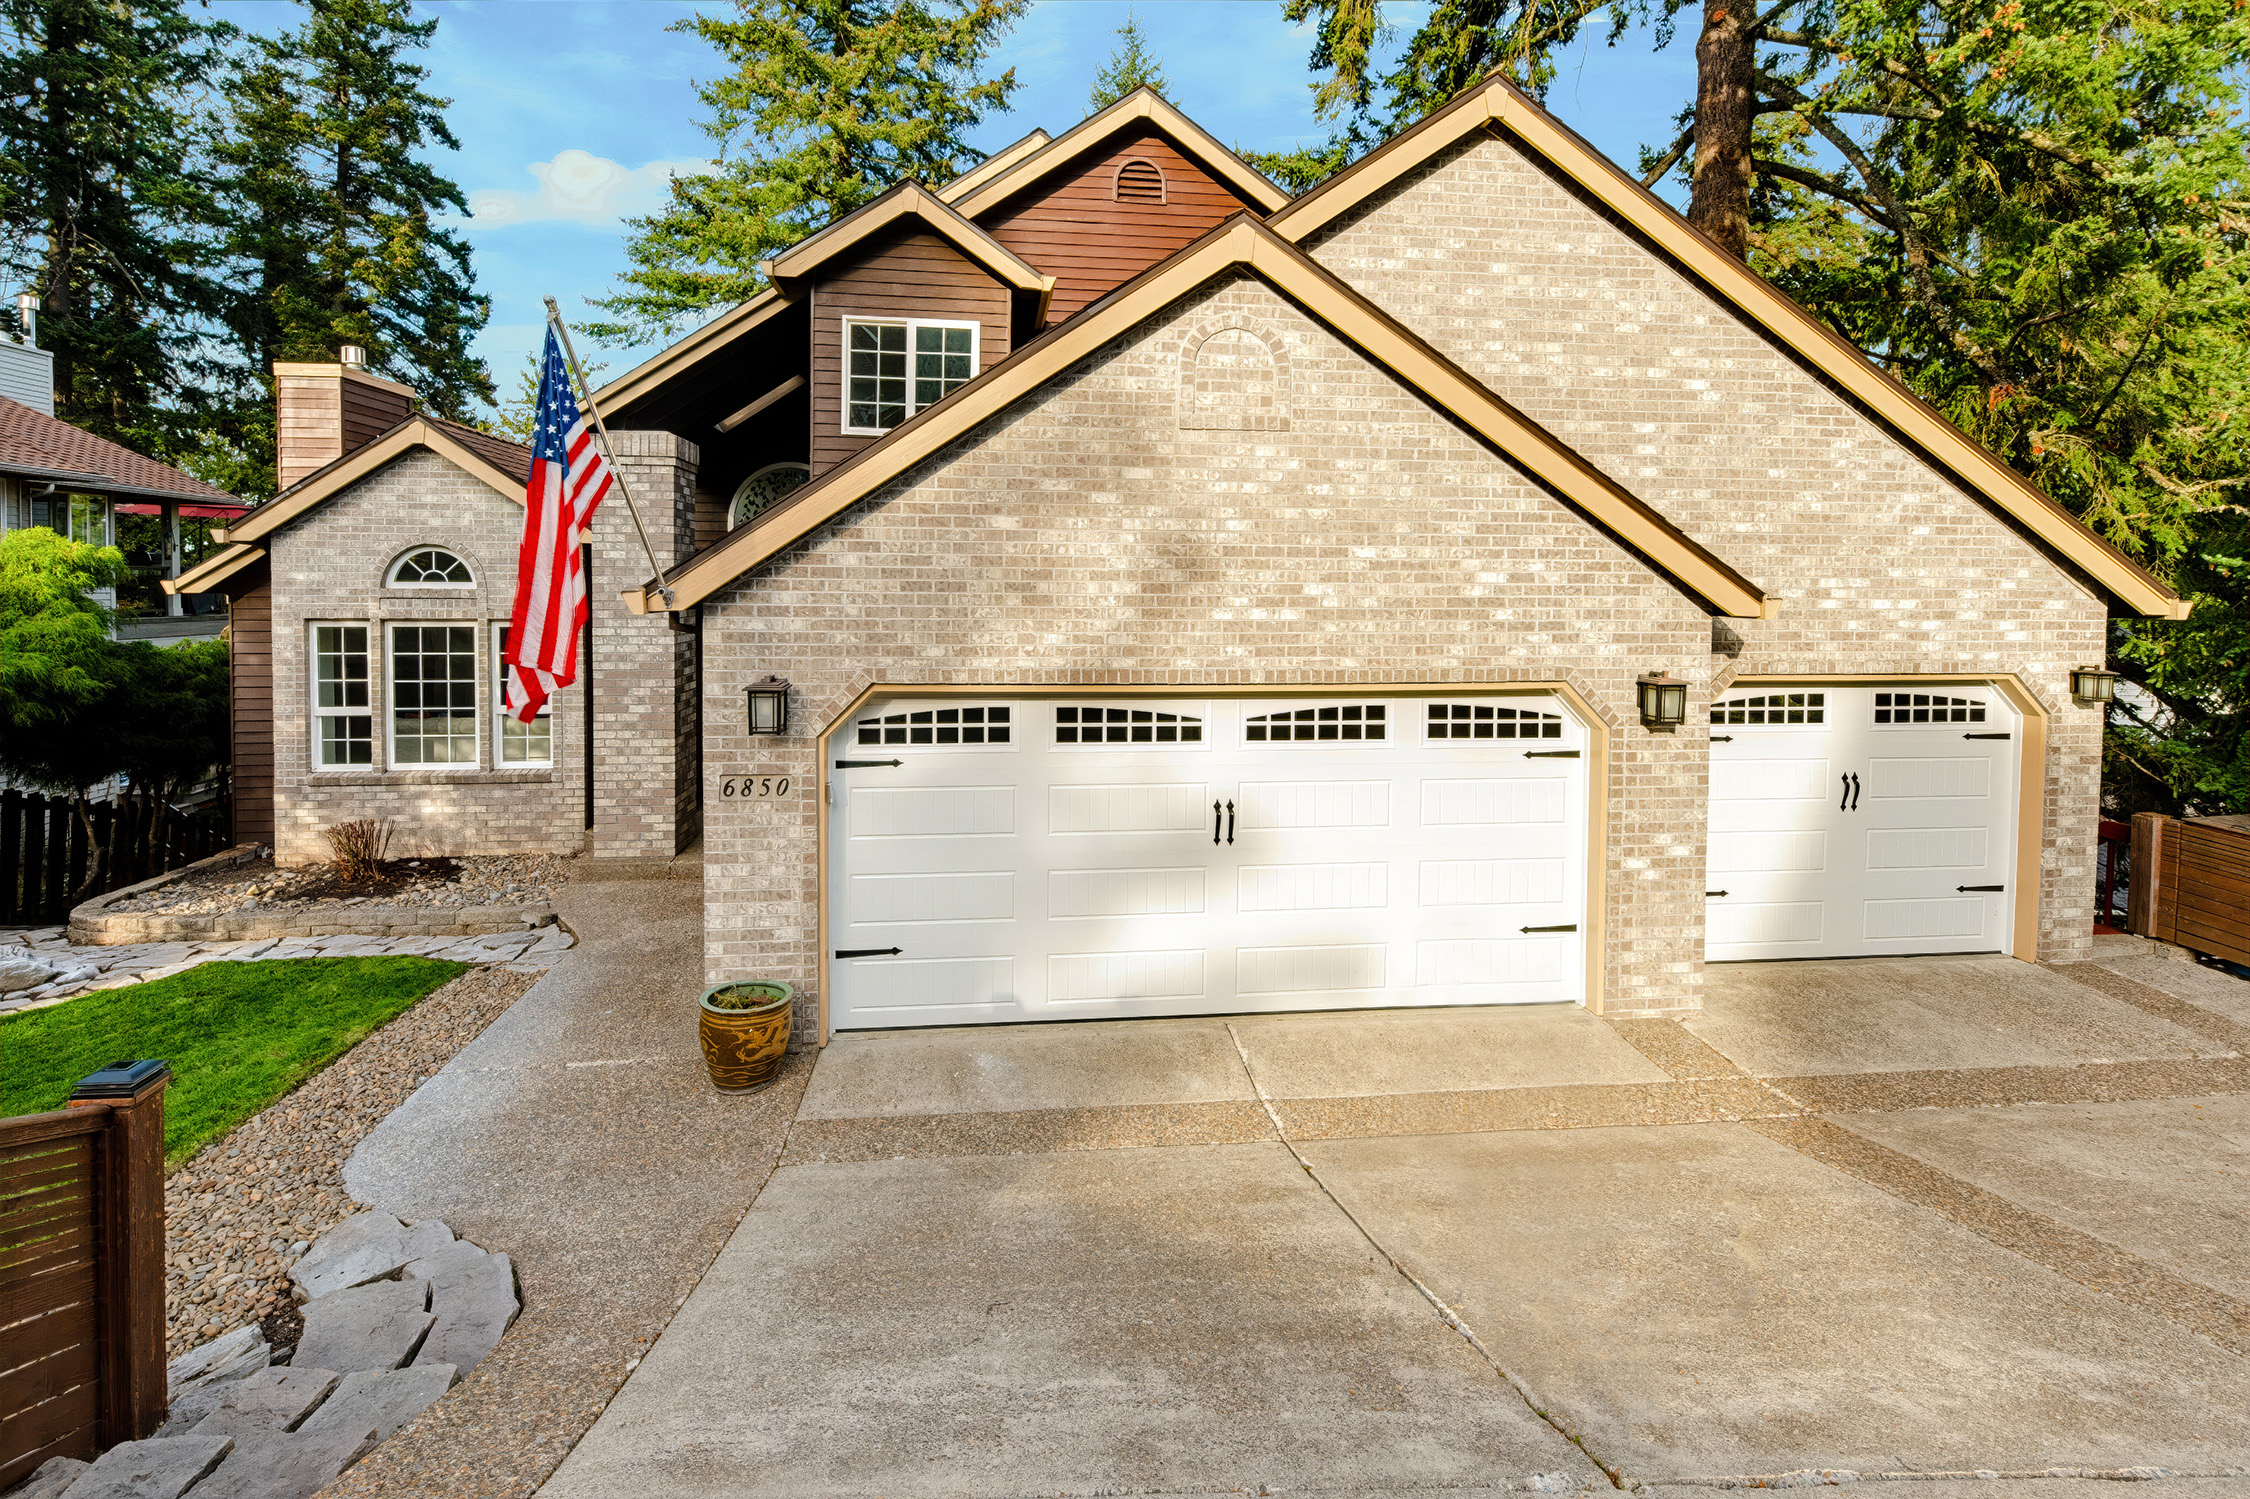
Living in the Treetops at 6850 Apollo Rd, West Linn
October 7, 2026West Linn Home with 4 Beds 3.5 Baths | 6850 Apollo Rd
Fall 2026 Market Update: What Rising Rates Mean for West Linn, Lake Oswego & Portland Buyers and Sellers
October 2, 2026Mortgage rates crossed 7% this fall. Here’s what that costs buyers in real dollars, how seller credits can help, and the latest Portland Metro, West Linn and Lake Oswego market data.
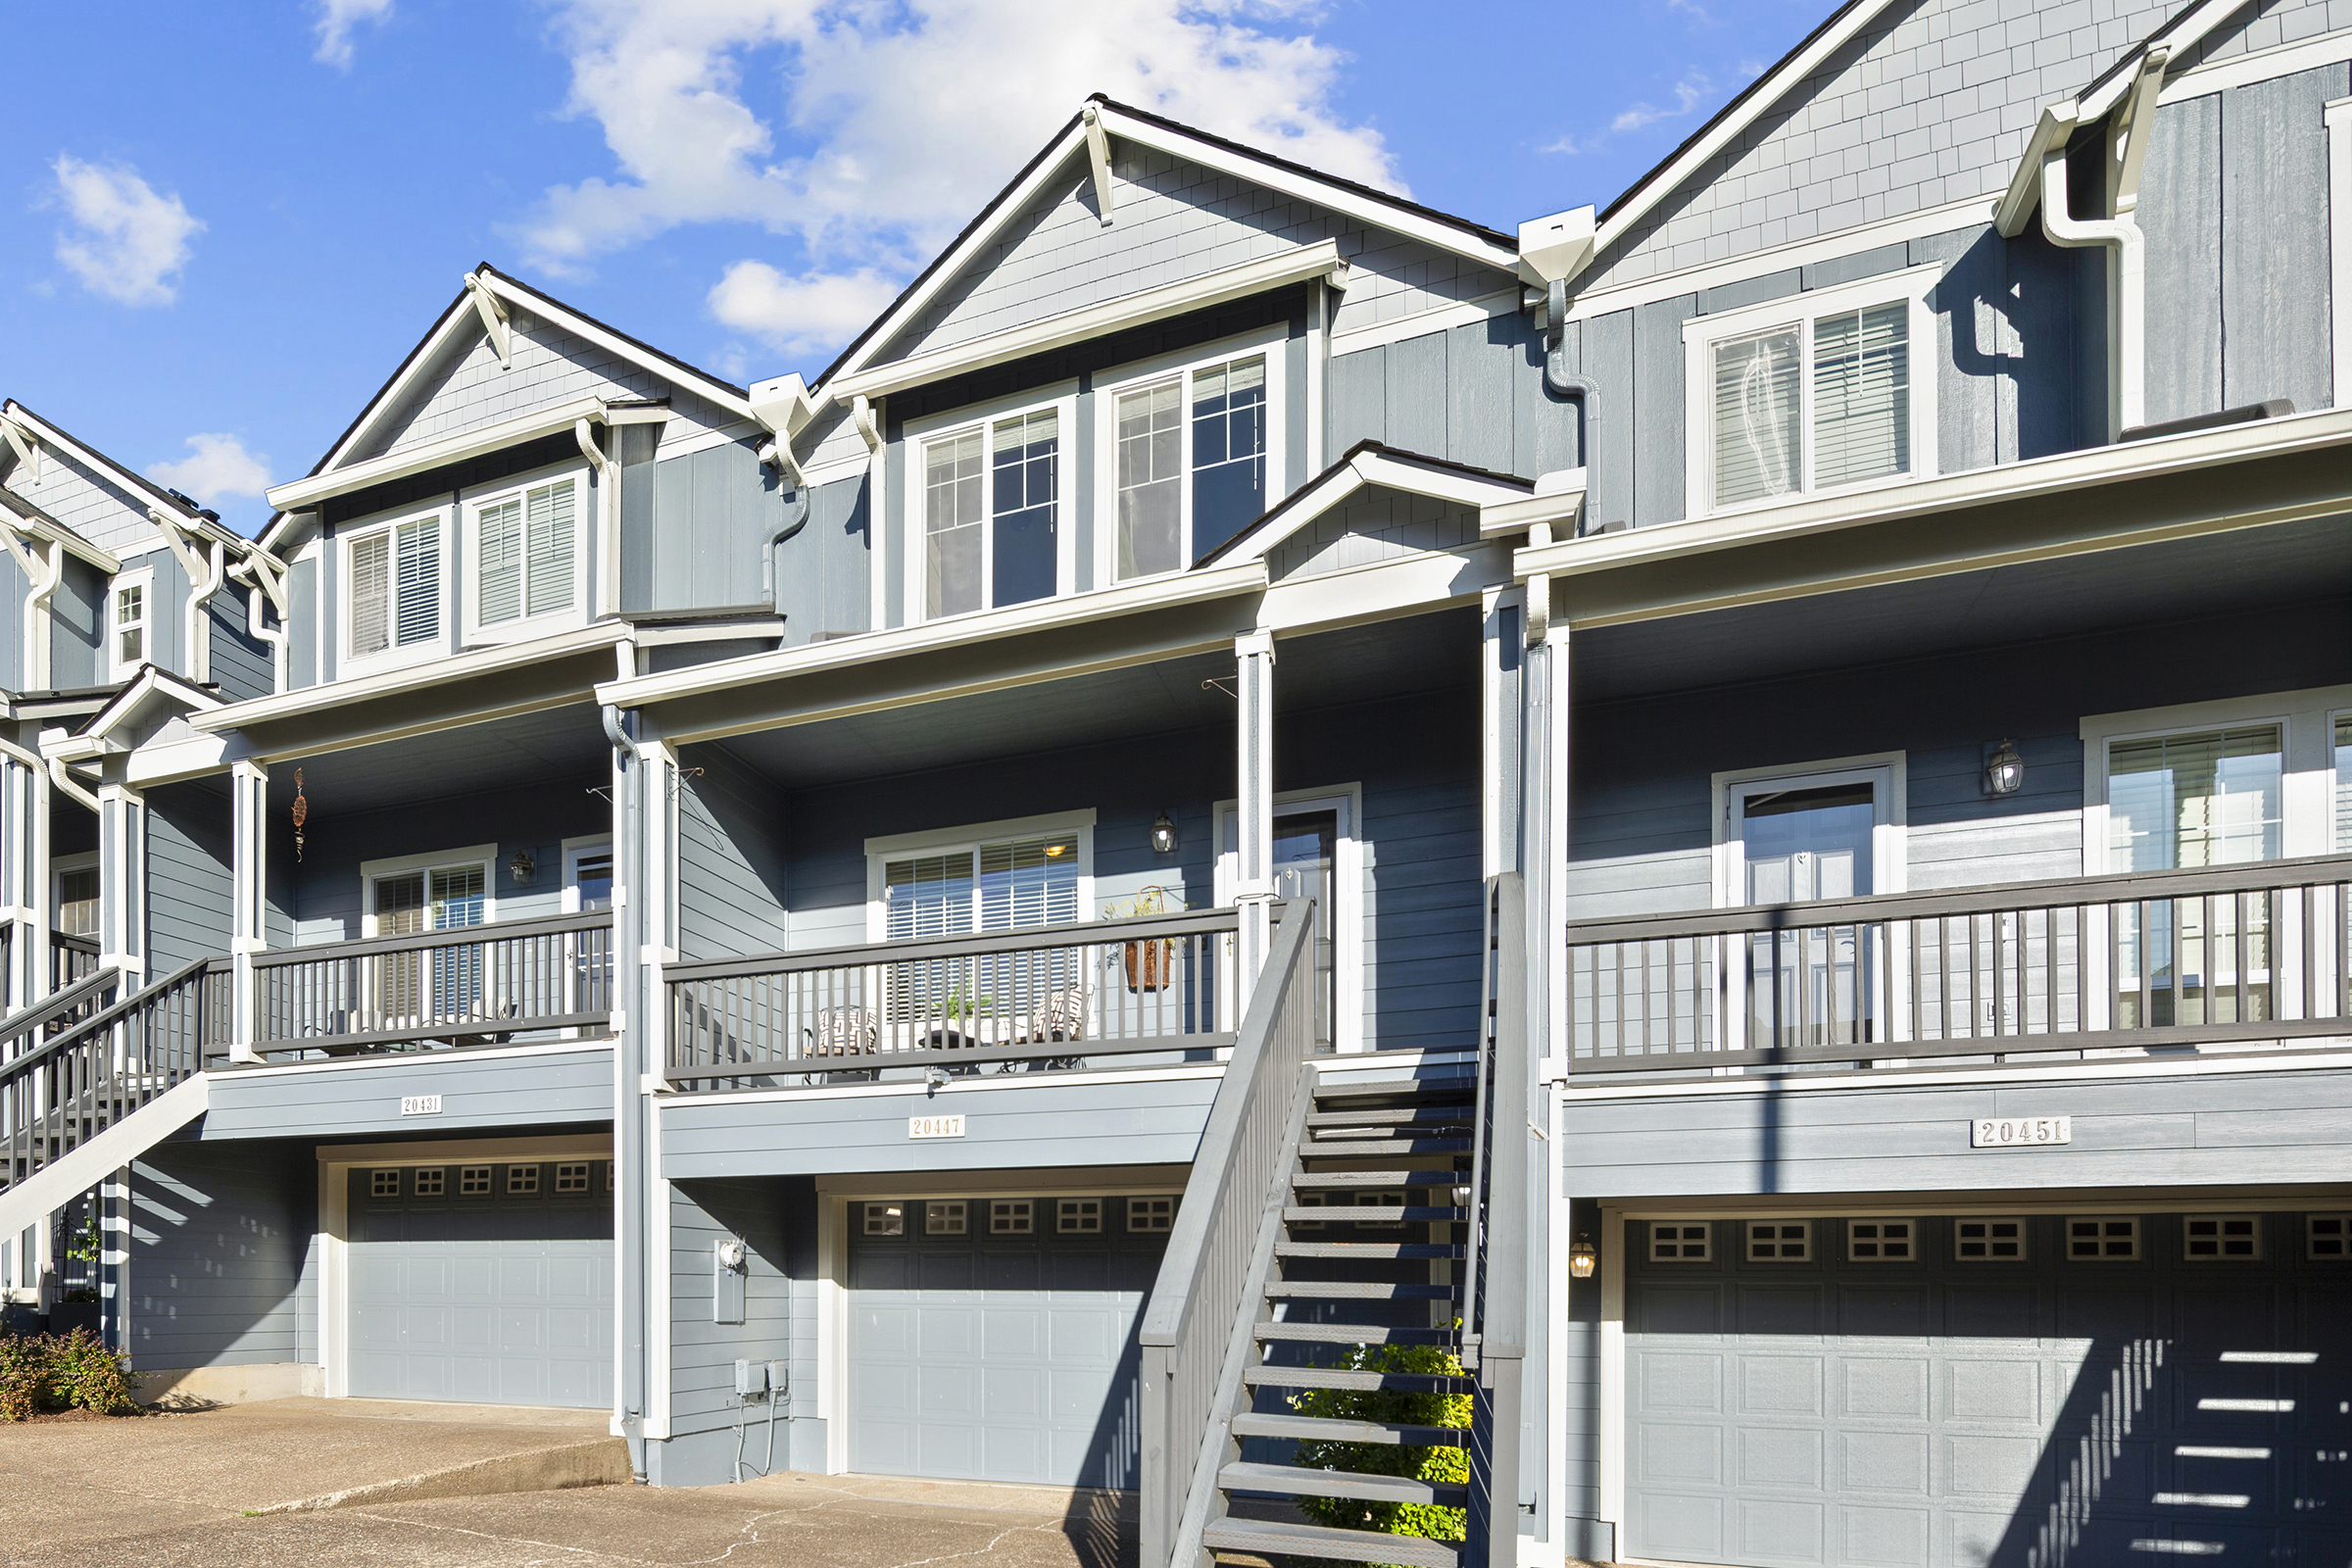
20447 Noble Ln West Linn Mt Hood Views Townhome
September 17, 2026West Linn Townhome with Mt. Hood Views & In-Law Suite | 20447 Noble Ln

August 2026 Housing Update
August 21, 2026Pricing and presentation still decide the outcome. Well-priced homes are selling quickly, while those listings that already took a price cut show buyers real negotiating room on stale inventory.
Historic Homes for Sale in Portland: Inside a Beautifully Updated 1908 Victorian in NE Portland’s Eliot – Boise Neighborhood
June 29, 2026132 NE Cook St, Portland, OR 97212
June 2026 Housing Update
June 25, 2026The market has softened. Here is what the data actually shows and what it means for you this summer.
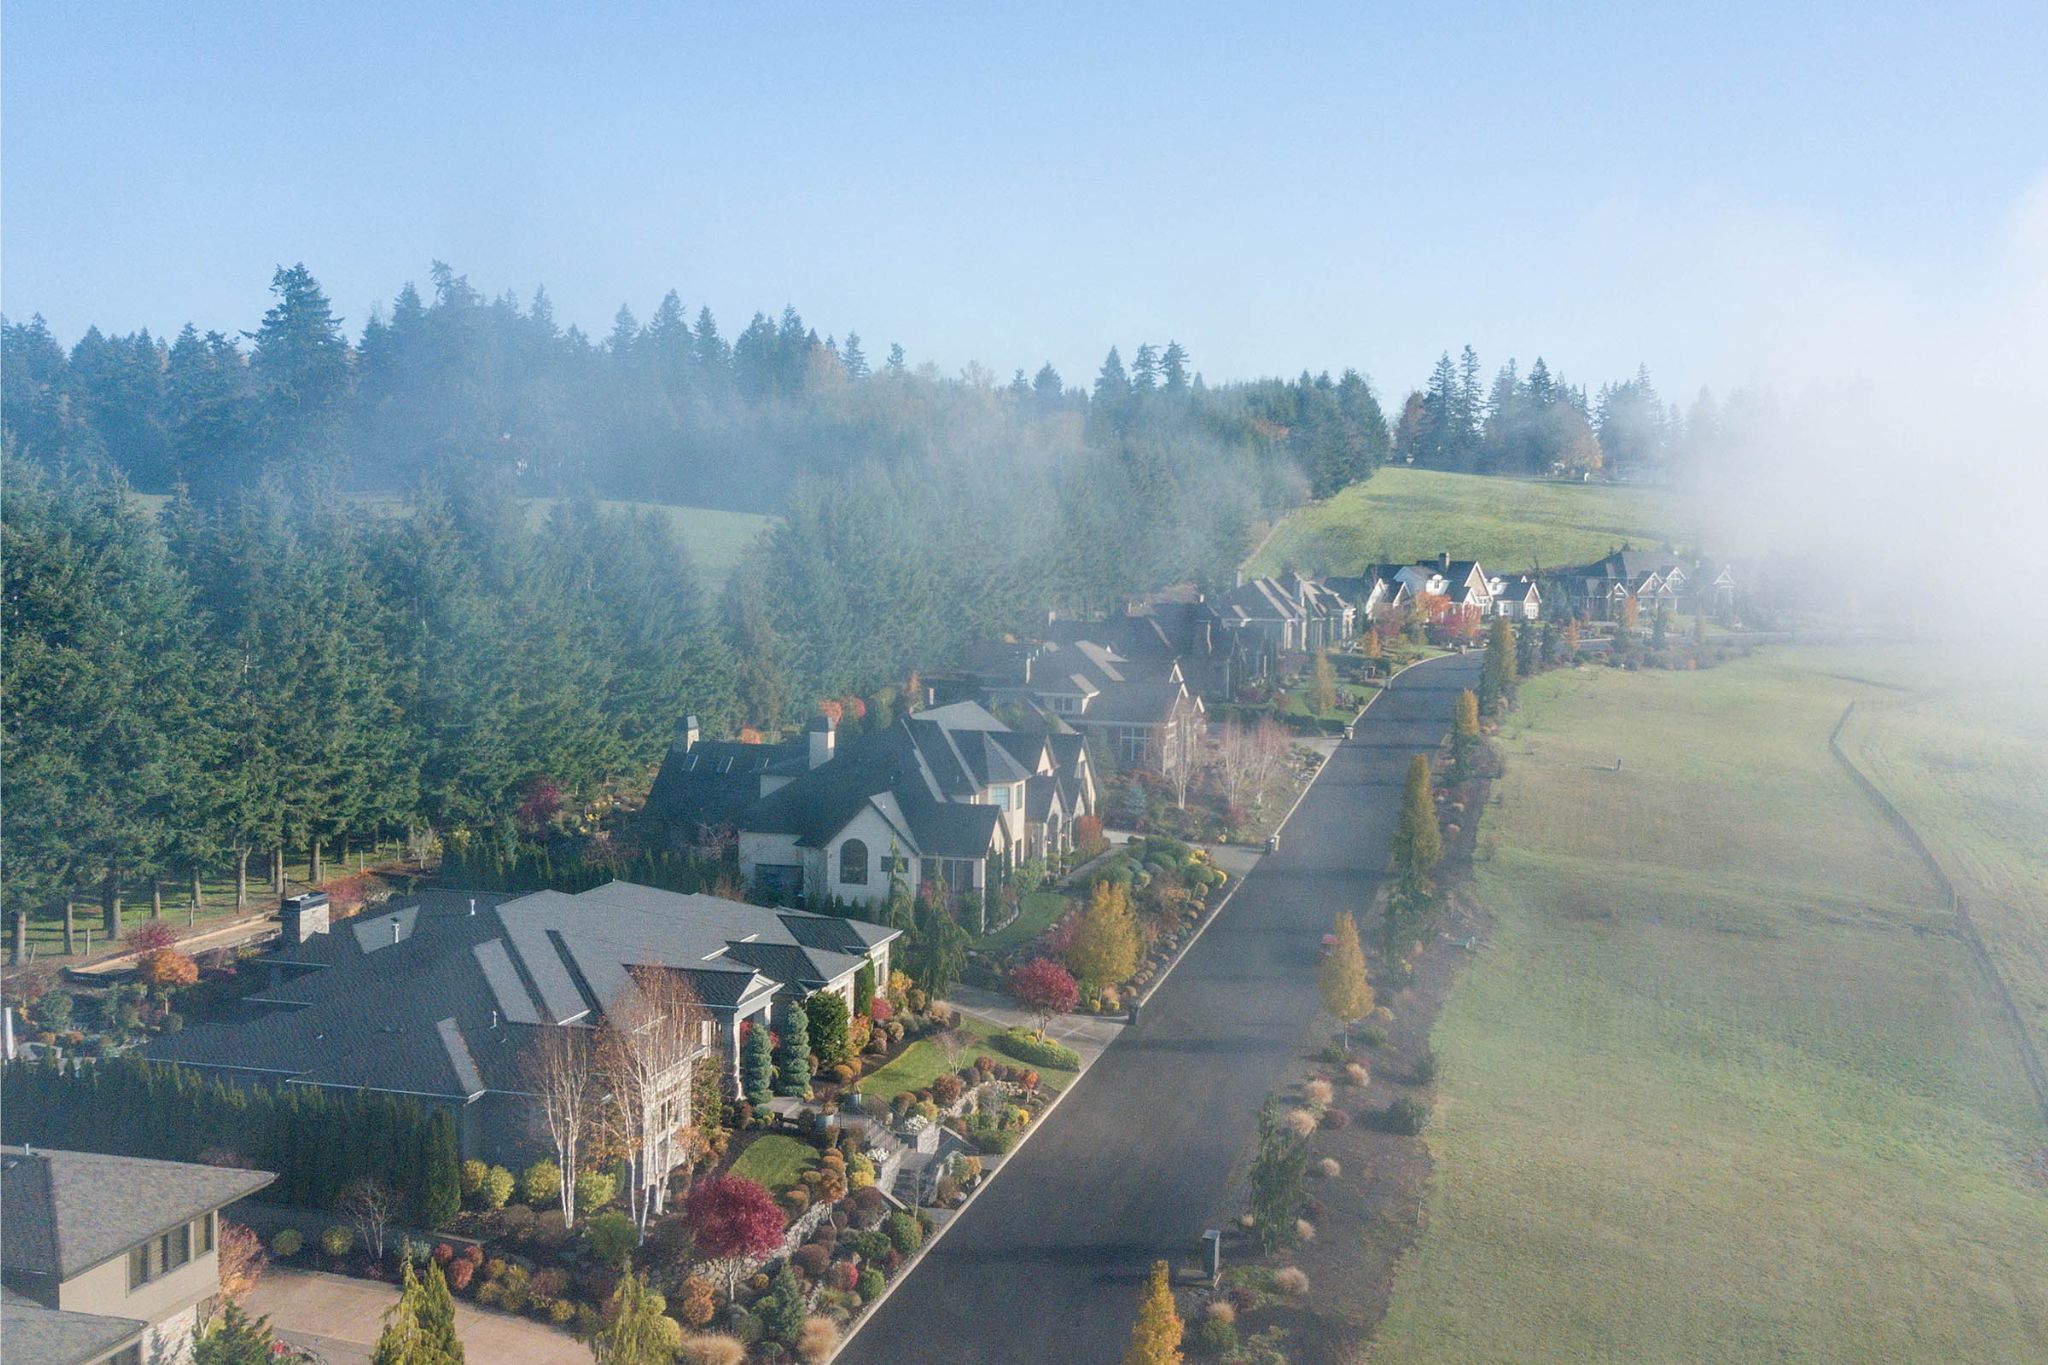
Moving to West Linn, Oregon in 2026: What Newcomers Should Know
December 22, 2025Maybe your current house fit your life five years ago. But that “for now” house you bought in 2020? It just can’t deliver on what you need in 2025. And that’s not just okay, it’s normal.
Mortgage rates are part of the equation, for sure. But the bigger question is:
What kind of home do you need to support the life you’re living now?

Why More Sellers Are Choosing To Move, Even with Today’s Rates
July 12, 2025Maybe your current house fit your life five years ago. But that “for now” house you bought in 2020? It just can’t deliver on what you need in 2025. And that’s not just okay, it’s normal.
Mortgage rates are part of the equation, for sure. But the bigger question is:
What kind of home do you need to support the life you’re living now?